Explore Crisil, a company of S&P Global
Formerly known as Global Research & Risk Solutions
January 08, 2026
 Blog
Blog
New age reconciliation framework for private market loans
January 08, 2026
Blog
Blog
Cranking up accuracy and transparency with practitioner-led controls
 Share


Reimagining reconciliation for private credit
Private credit is growing aggressively. Investors are allocating billions into direct lending, unitranche structures, mezzanine capital, asset-backed financing and structured credit. However, something is slowing down net asset value (NAV) reporting, inflating operational cost and quietly leaking return points.
With most middle- and back-office teams still managing these assets using tools designed for liquid markets, it is clear now that the process of reconciliation needs an upgrade.
After having worked closely with private loan operations, one thing is clear to us:
Private market loans break into places where traditional systems usually don’t bother to check.
In fact, illiquid, bespoke and heavily negotiated loans create reconciliation headaches that simply don’t exist with syndicated or traded debt.
Why private market loan reconciliation is more complex than ever
Unlike liquid credit, private loans are highly customized, and every deal has its own contractual terms. That complexity becomes brutally stark when performing reconciliation such as par, interest, principal and transactions.
Let us try to understand the practical challenges:
a) System mismatch: Silent destroyer of accuracy
The loan lifecycle touches too many systems.
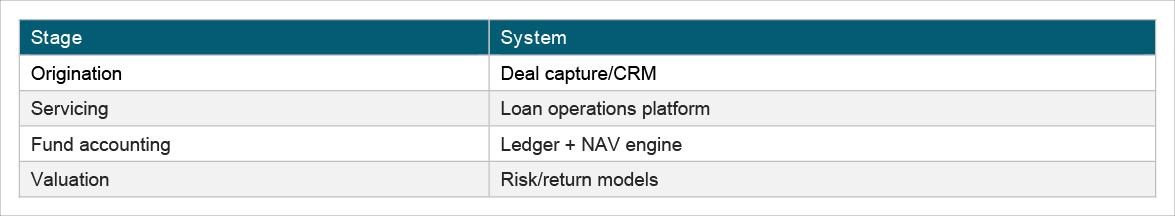
Each system interprets accruals, rate resets, amortization and payment-in-kind (PIK) behaviour differently. So, when numbers don’t match, nobody is wrong because each system operates based on a different point of interpretation.
This creates issues such as:
- Accrual mismatches across reporting layers
- Cash getting classified as principal in one system, interest in another
- Amortization tables drifting with every amendment
- Accounting ledger showing a reality servicing never recorded
This is a challenge most operational leaders have experienced firsthand.
b) Bespoke loan terms break standard operating logic
Unlike public credit, private loans aren’t commoditized. No two deals behave the same and constantly evolving terms make it nearly impossible for legacy systems to maintain alignment. Reconciliation becomes a daily firefight.
Here’s what standard software struggles with:
- Custom fees and waterfall distributions
- Rate step-ups linked to covenant performance
- PIK toggles with optionality
- Amendment-driven resets and new schedules
- Special collateral rules requiring override logic
Traditional systems were designed for standardization.
In other words, the asset class breaks the software, not the team.
c) Manual interventions: Where the real value leaks
Despite the rise in automation tools, Excel is still the backstop. And nothing introduces hidden risks like a one-cell override during high-pressure hours.
A single line adjustment can translate into:
- Incorrect rate of return (IRR)
- Wrong principal amortization
- Valuation drift after event resets
- Investor report misstatement
The small fix isn’t small. It just seems so the moment it is implemented.
The hidden cost of inefficient reconciliation
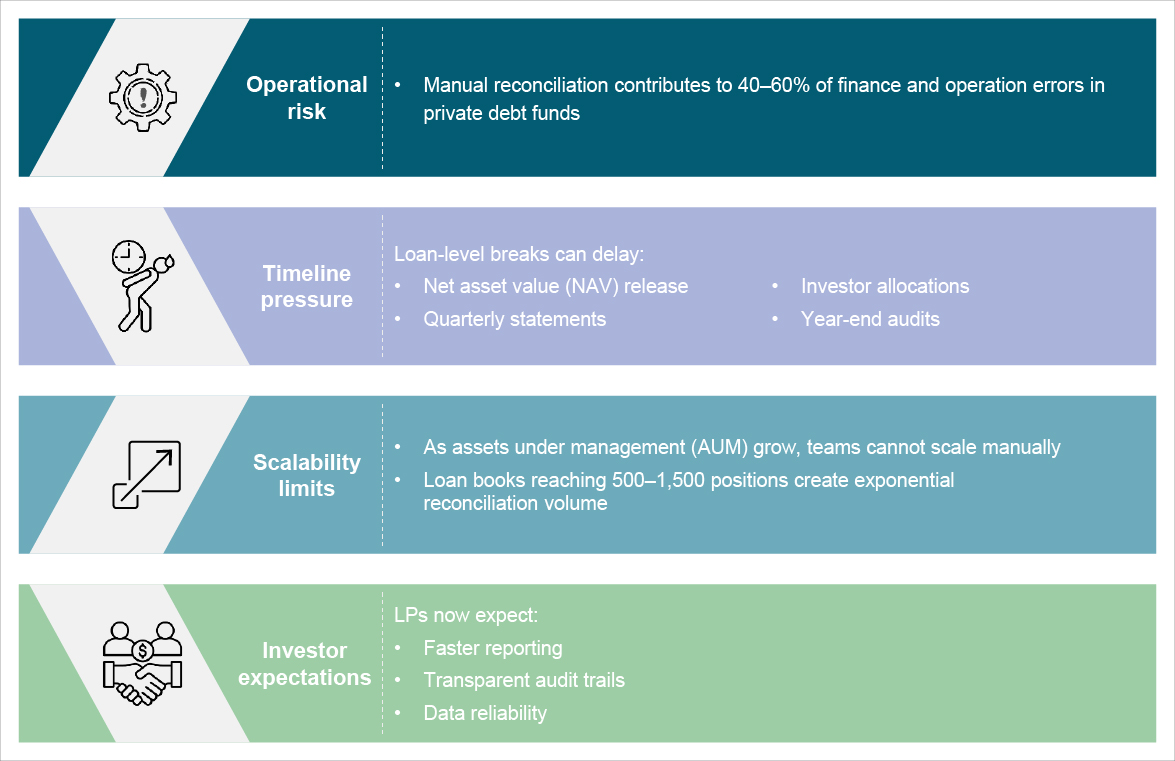
In private market loan operations, reconciliation is the largest source of operational friction, creating challenges such as:
Key Takeaway
Reconciliation breaks in private credit are rarely driven by a single error. They typically emerge from misaligned processes, event timing gaps, and system silos—where each platform is “right” on its own, but wrong in aggregate.
What seemed like minor mismatches were quietly building up in the background, signalling the need for a more sophisticated and modern reconciliation framework.
What a modern private market loan reconciliation framework looks like
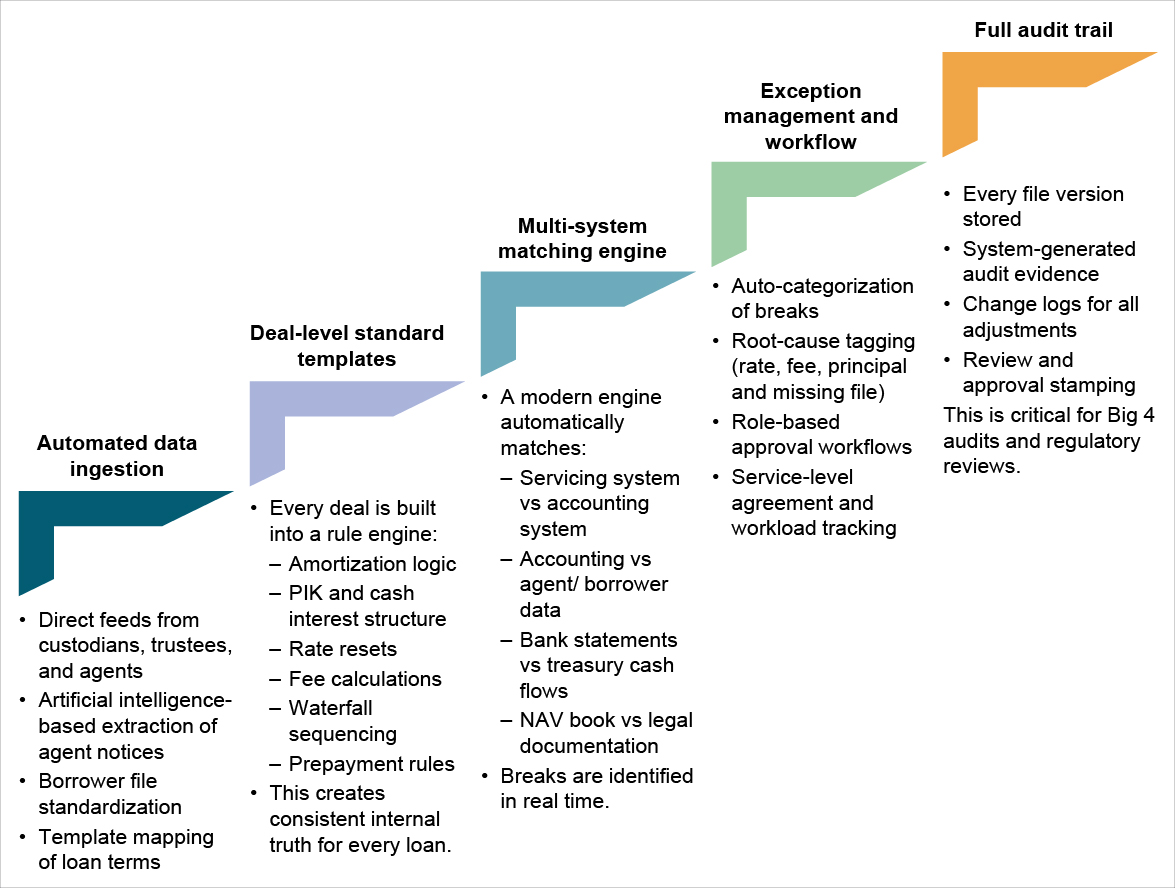
The next-generation reconciliation framework must be data-driven, template-based and exception-focused.
Leaders in the industry follow these pillars:
Automation drives quantified impact
Private market firms see substantial improvements once reconciliation is redesigned.
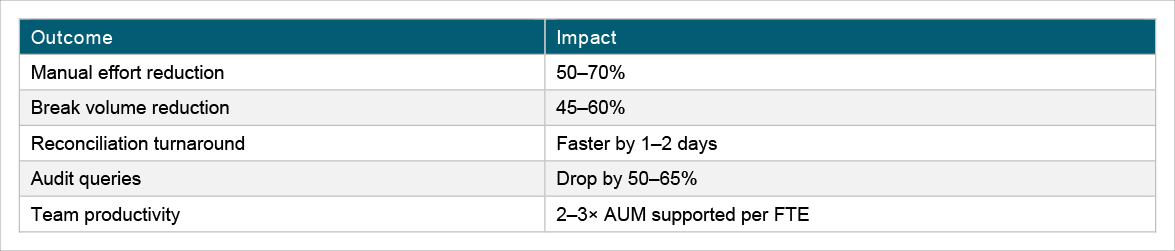
Automation strengthens operational excellence and investor trust.
Conclusion
Private market loans are extremely complex and outdated reconciliation methods cannot keep up with the requirements of such loans.
To stay on top of the game, managers need:
- Data automation
- Standardized templates
- Reliable matching logic
- Exception-first workflows
- Strong audit infrastructure
Reconciliation is no longer a back-office task. It is a strategic enabler that determines operational efficiency, investor trust and valuation accuracy.
References:
How AI could reshape the asset management industry | McKinsey
Private Markets | S&P Global
https://www.aima.org/article/private-credit-investor-forum-2025-key-takeaways.html
https://pitchbook.com/news/reports/april-2024-us-leveraged-loan-index-monthly-wrap