Explore Crisil, a company of S&P Global
Formerly known as Global Research & Risk Solutions
February 03, 2026
 Blog
Blog
The Blue Owl turning point in private credit
February 03, 2026
Blog
Blog
As the merger of BDCs unravels, valuation and liquidity worries follow, so do value-investing opportunities
 Share


Over the past decade, private credit has emerged as the fastest-growing asset class in global financial markets, offering investors a unique opportunity for diversification and attractive returns.
At the heart of the private debt ecosystem is direct lending, which represents the largest and most established segment of private credit. One of the primary vehicles for direct lending is the Business Development Company (BDC).
Understanding BDCs Landscape
BDCs can be either publicly listed or private, but both are regulated by the Securities and Exchange Commission (SEC) and adhere to similar investment strategies and reporting standards. However, there are significant differences between the two:
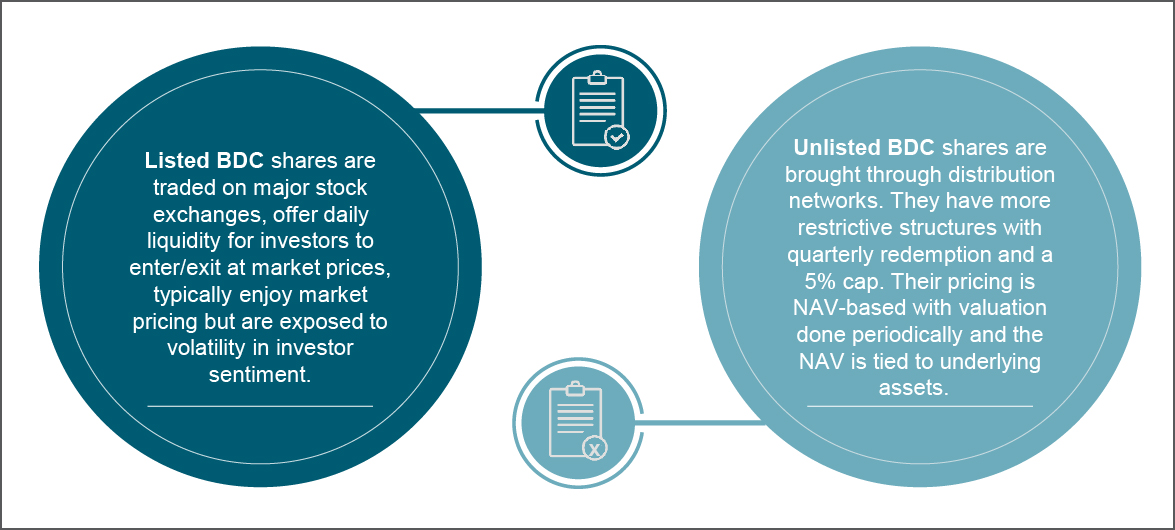
Despite investing in similar underlying assets, traded and non-traded BDCs behave differently. While the traded vehicles have high visibility and liquidity, the non-traded ones are distribution-driven and less volatile. This dichotomy between traded & non-traded vehicles makes BDCs a complex landscape for investors to navigate.
BDCs has been the most favorite investment in the income world, offering double digit yields fueled by rising interest rates and a vacuum in middle market lending. However, a perfect storm of economic slowdown, tighter spreads and shifting investor sentiment has turned the tide.
Fitch1 signaled a definitive downturn, warning of deteriorating credit quality and erosion of covenant protections as BDCs sacrifice underwriting standards to compete in high-rate environment. This structural decay, paired with narrowing spreads and a cooling economy triggered a perfect storm in late 2025.
The last quarter of 2025 saw a sharp erosion in BDC share prices while investor redemptions hit the highest level in 4Q25. While the market was already on edge due to shifting Fed policy, the panic was solidified by the high-profile merger failure at industry titan Blue Owl. The collapse of their massive consolidation plan shattered investor confidence, turning a localized deal fallout into a sector-wide contagion.
1 Source: https://www.fitchratings.com/research/corporate-finance/fitch-ratings-completes-peer-review-of-eight-us-bdcs-30-06-2025
Blue Owl Misfire: Structural Failure
In Nov 2025, Blue Owl Capital - one of the industry’s most respected heavyweights - faced a rare and public stumble. The firm attempted to merge its flagship listed BDC, Blue Owl Capital Corporation (OBDC, AUM of $17.1 billion), with its unlisted sibling, Blue Owl Capital Corporation II (OBDC II, AUM of $1.7 billion).
The proposed all-stock merger would have allowed investors in OBDC II to exchange their shares for OBDC shares at the current market price.
The merger was expected to offer investors better liquidity, scale, cost synergies and potentially higher returns given the similarities between OBDC and OBDC II, such as:
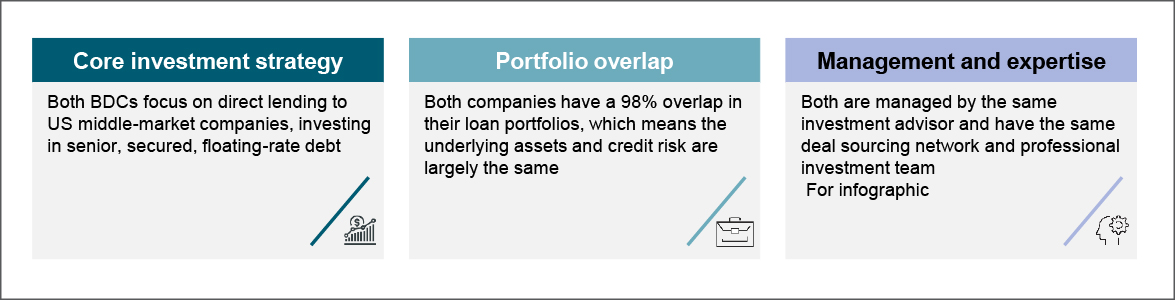
But within weeks, Blue Owl had to terminate the merger as OBDC shares plunged over 20% below the net asset value driven by negative investor sentiment in a milieu of market uncertainty, economic slowdown and concerns over structural changes after dilution.
The Fallout:
- Haircut Scare: Because OBDC was trading at a 20% discount to its Net Asset Value (NAV), unlisted investors in OBDC II realized they were effectively being forced into a massive paper loss.
- Redemption Freeze: Blue Owl temporarily paused redemptions for OBDC II ahead of the merger, sparking panic among retail investors who had been promised “semiliquid” access to their cash.
- The Reversal: Following a sharp decline in share price and mounting investor outcry, Blue Owl abruptly canceled the merger on November 19, 2025.
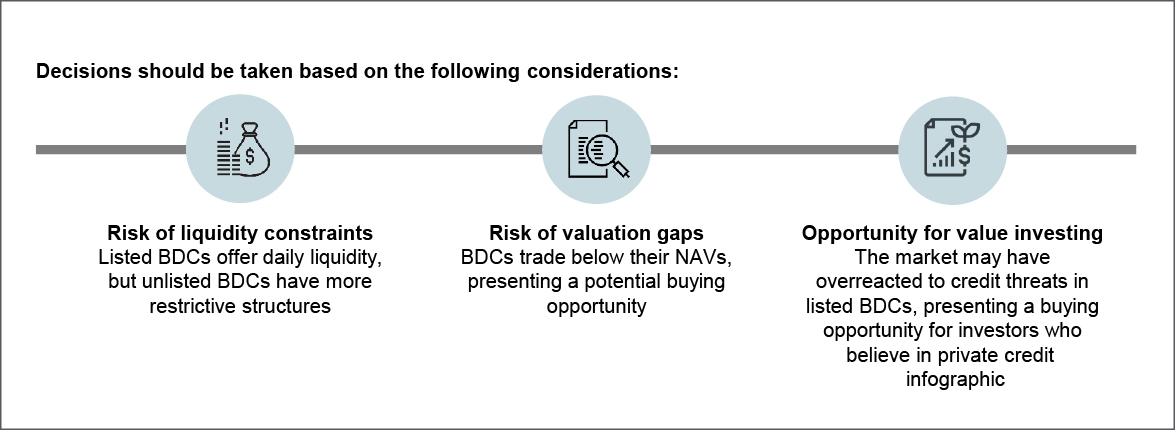
The Blue Owl merger failure has sent shockwaves through the private credit markets and raised concerns about liquidity constraints, valuation gaps and redemption mechanics in semi-liquid investment vehicles.
Aftermath: Market Uncertainty & Decline in inflows:
The result of valuation gaps, rate cuts and market volatility is a noticeable cooling of investor enthusiasm. For the first time in years, BDC inflows are stalling.
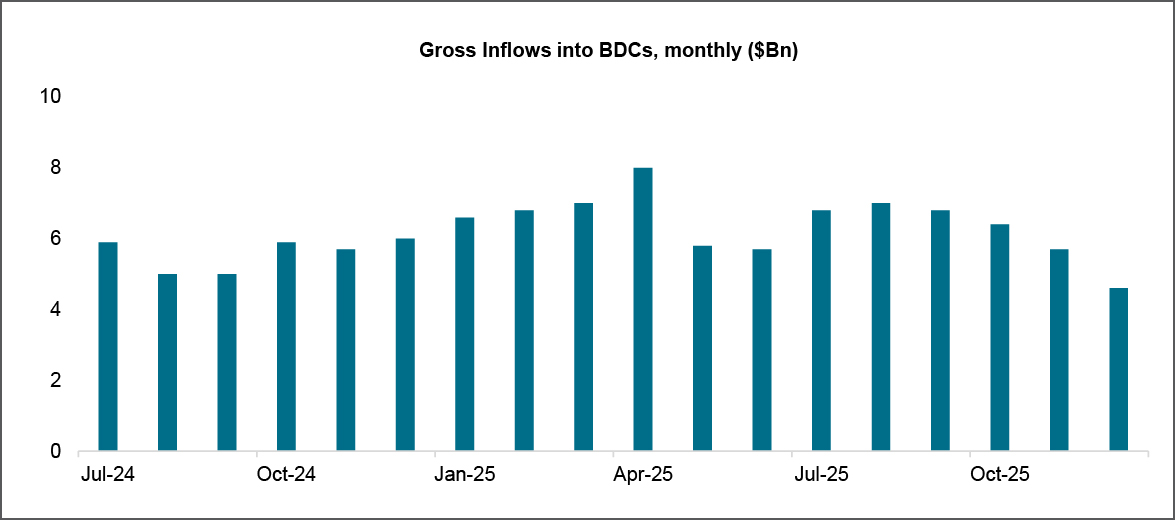
- Yield compression: With traditional fixed income and high yield bonds offering safer alternatives, as spreads tighten, the risk-taking mentality is fading.
- Retail retreat: The Blue Owl merger event has made retail investors and financial advisors wary of non-traded BDCs. If you can’t exit when you want to, the 10% yield starts to look like a trap. Funds managed by Apollo Global Management, Ares Management and Blackstone all suffered an uptick in redemption requests in 4Q25.
- Deployment Pressure: Institutional investors are worried about hyperscaling. Large BDCs are under immense pressure to put billions of dollars to work, leading to looser underwriting standards and lower borrowing quality.
The Road Ahead: Risks & Opportunities
The BDC market is not dying but maturing. The tailwinds are gone, and investors are distinguishing between “best in class” managers with disciplined underwriting. By understanding the underlying holdings, redemption mechanics and market sentiments, investors can make informed decisions and navigate the ever-changing landscape of private credit markets.
Conclusion
The termination of the Blue Owl merger is a turning point in private credit markets as it has foregrounded their complexities and nuances.
While the fall in the listed BDC’s shares may have triggered apprehensions about liquidity constraints, valuation gaps and redemption mechanics, it presents a potential investment opportunity for investors who believe in the long-term prospects of private credit.
As this asset class continues to evolve, it is crucial for investors to stay informed and adaptable.
By acknowledging the complexities of the BDC landscape and the interplay between listed and unlisted vehicles, investors can position themselves for success in this dynamic and often unpredictable market.