Explore Crisil, a company of S&P Global
Formerly known as Global Research & Risk Solutions
May 06, 2026
 Case study
IFRS 9 credit and haircut model development for HNI portfolios
May 06, 2026
Case study
Case study

 Share


Objective
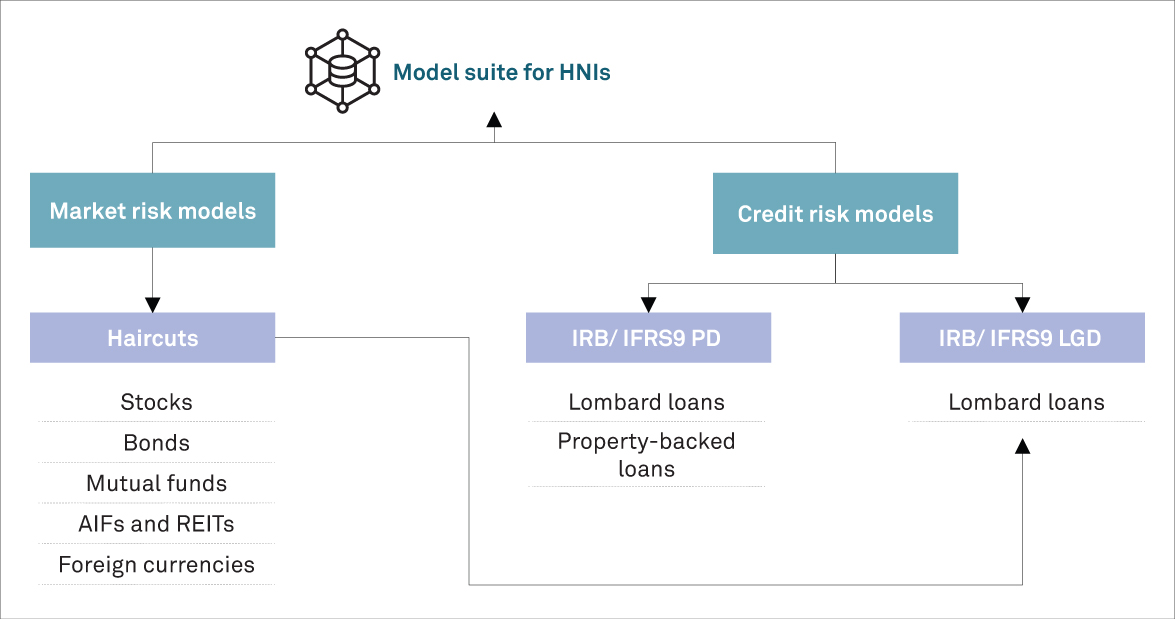
- End-to-end development and delivery of a suite of market risk and credit risk models
- Development of haircut, IRB and IFRS 9 PD/ LGD models in compliance with Bank of Thailand guidelines
Our solution
- Haircut models
- We determined appropriate haircuts to be used for collateral valuation when pledging assets for Lombard loans and as an input factor for LGD models
- Equity haircuts were determined using a non-parametric historical VaR-based methodology with appropriate time horizons and confidence levels
- Bond haircuts were determined by simulating future interest rate scenarios and pricing hypothetical default-free bonds
- IRB/ IFRS 9 PD models
- Statistical modelling was blended with expert judgment to address the low/limited default data in the portfolio
- Proxy defaults and risk rankings were defined using questionnaire-responses provided by RMs, business and risk officers
- PDs were determined using statistical analysis and expert inputs, followed by calibration
- Macro-economic projections and TTC-to-PiT estimates were used
- IRB / IFRS9 LGD models
- Haircut models were used to estimate recoveries
- Appropriate stress factors were applied to current outstanding balances and collateral values to estimate collateral value at default
- Recoveries were determined based on collateral pledged and liquidation windows
Impact
- A new haircut model replaced existing haircuts for valuing collateral pledged for Lombard loans
- The bank is planning to move from SA to F-IRB/ A-IRB; parallel monitoring will be done to evaluate RWA impact
Portfolios covered
- High-net-worth individuals (HNIs) - Lombard and property-backed loans